Intellectual
Capital
Digital Intelligence.
Consistent Outcomes.
Our intellectual capital is built on technology, customer insights, process improvements, analytics, governance frameworks and institutional knowledge. As banking becomes more digital-first, technology is no longer just an enabler. It is central to how the Bank delivers services and engages with customers. These capabilities help improve customer experience, strengthen efficiency and risk management and support sustainable growth.
SDGs
Material Topics
- Cybersecurity and Data Privacy
- Digitalization
- Product Design and Innovation
Stakeholders
Investors/
Shareholders
Customers
Employees
Digital Banking Platforms
DLite: Transforming Retail Banking through Digital Engagement
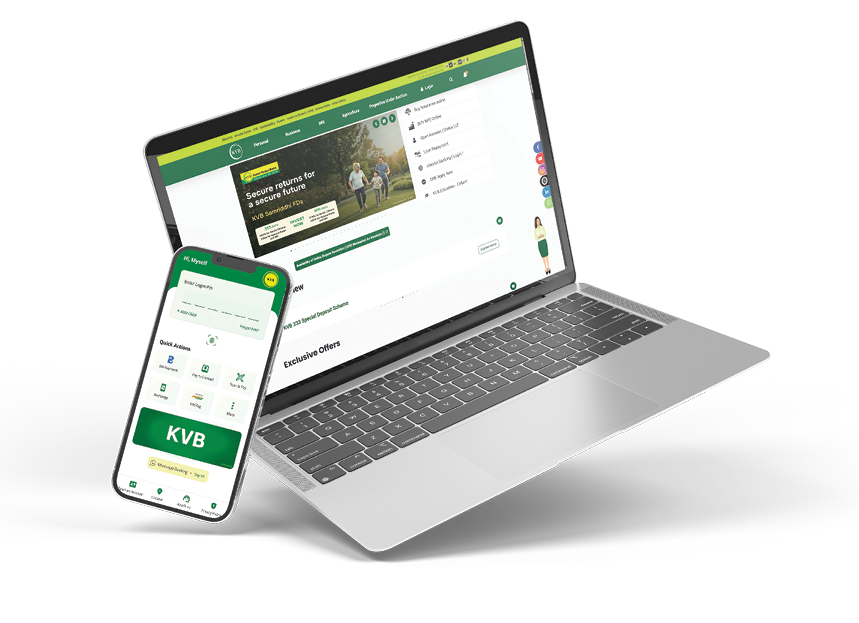
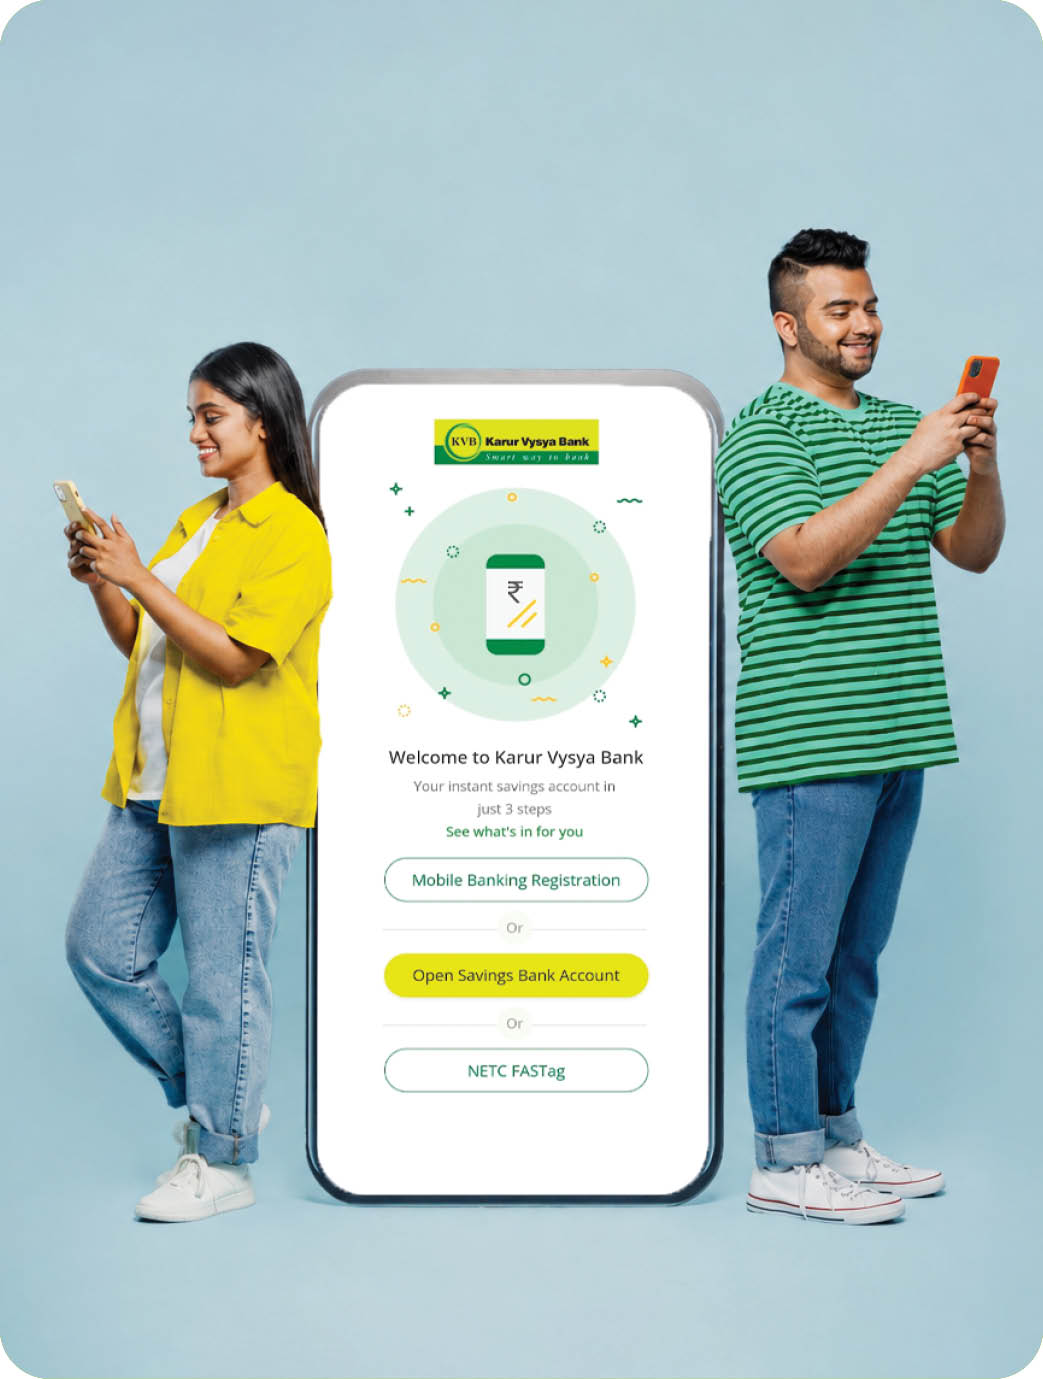
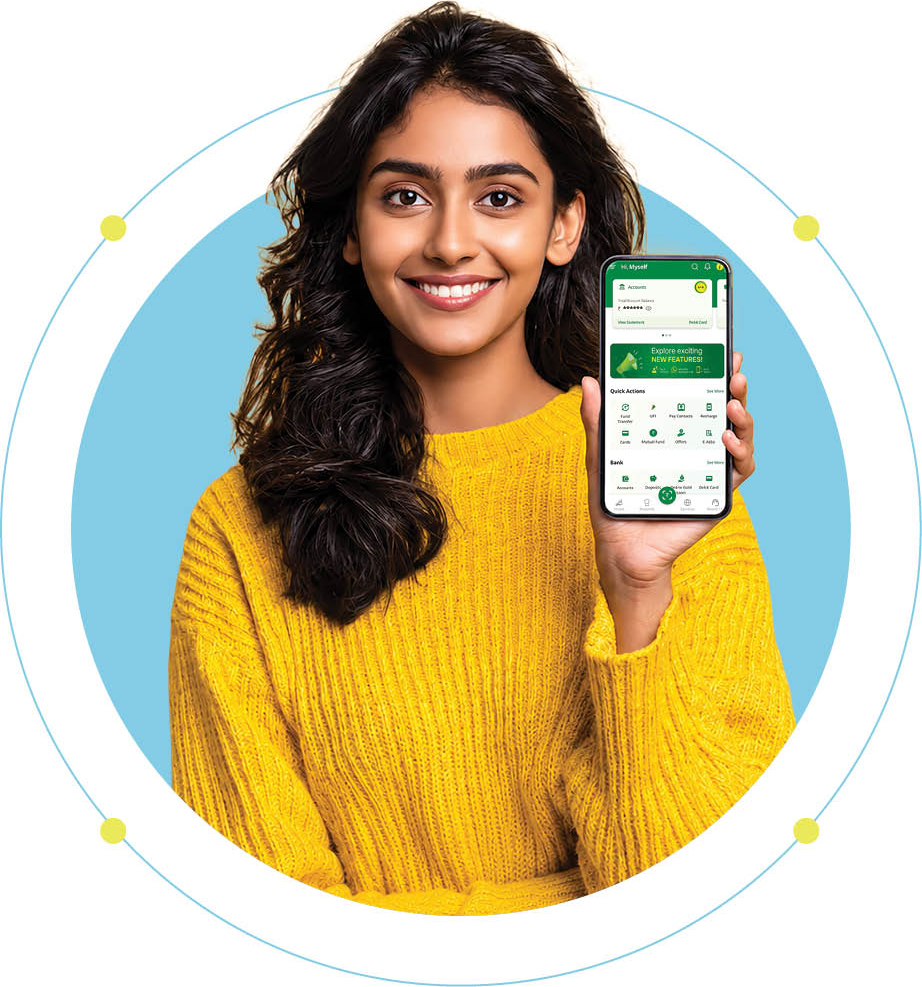
DLite has emerged as the Bank’s flagship retail banking platform and a key intellectual capital asset. With more than 150 banking services in one digital ecosystem, the platform has changed how customers interact with the Bank. It also creates a scalable base for customer acquisition, engagement and servicing.
The platform supports customers across the lifecycle, including digital account opening, Video KYC, digital Re-KYC, payments, transfers, and several self-service banking features. The introduction of Instant Video KYC has improved onboarding efficiency by enabling near-instant account activation and smooth conversion of digitally onboarded customers from Low KYC to Full KYC status.
Key capabilities enabled through DLite include:
- Accelerated customer onboarding and activation
- End-to-end self-service banking across a wide range of products and services
- Intuitive user experience through enhanced interface design, easy navigation and integrated search functionality
- Seamless and secure digital access with simplified login capabilities
- Convenient payment and transfer services, including Pay-to-Contacts and single-click payment functionality
- Personalized and dynamic offers tailored to customer needs
- Banner management utility that enables quick updates and management of promotional banners
- Improved accessibility and convenience through anytime, anywhere banking
Beyond servicing, DLite functions as an important source of customer intelligence. Platform interactions generate behavioral insights that support sharper segmentation, personalized engagement and more relevant product recommendations.
FY 2025-26 Highlights
4.8/5
Play Store Rating
4.6/5
App Store Rating
7 Mn+
Total Downloads
2.5 Mn+
Monthly Average Transactions
1 Mn+
Monthly Active Users
4.17 Lakh+
Accounts Opened
Next Phase of Ev lution
Building on its strong adoption, the Bank is undertaking a comprehensive modernization program aimed at transforming DLite into an intelligent financial engagement platform. The roadmap includes migration toward a microservices-based architecture and a decoupled technology framework that will improve scalability, accelerate feature deployment and enhance platform agility. Artificial intelligence and advanced analytics are being integrated to deliver hyper-personalized customer experiences, contextual product recommendations and dynamic engagement capabilities.
The next phase shall include personalized push notifications, behavioral analytics, intelligent feature placement, financial wellness dashboards, net worth tracking capabilities, AI-generated financial insights, loan eligibility tools, rewards and gamification features, chatbot-enabled servicing and virtual assistance.
The Bank is also extending its digital reach to emerging customer segments through a dedicated Gen Z banking initiative developed in partnership with a fintech organization. The platform combines digital account opening capabilities with financial and non-financial services designed to engage younger customers and establish long-term banking relationships.
KVB Corp:
Reimagining Corporate and MSME Banking
The launch of KVB Corp marks a defining step in the Bank's corporate banking evolution. More than a mobile application, it is a full-stack digital ecosystem built exclusively for corporate and MSME customers, designed to make KVB the primary operating bank for businesses. Designed as an integrated omni-channel platform, KVB Corp combines mobile and internet banking capabilities within a unified experience tailored to business banking needs.
In an era defined by rapid digital transformation and evolving cyber threats, trust, resilience and security are fundamental to our business strategy, guiding decisions at every level of the organization. The Bank continues to invest in scalable and resilient technology infrastructure designed around reliability, availability and operational continuity to support seamless customer experiences across digital touchpoints.
Key Features
- Unified access to mobile and internet banking channels
- Streamlined account management, including cheque-related services
- End-to-end transaction banking capabilities, covering IMPS, NEFT, RTGS, standing instructions and bill payments.
- Integrated loan, deposit and tax payment services, including Income Tax and GST payments
- FASTag and other digital payment solutions
- Enhanced security and profile management with user controls, session monitoring and transaction limits
- Digital self-service capabilities such as e-statements, Form 26AS access, mutual fund services and request tracking
- Real-time alerts, notifications and value-added services, including credit card and gift card-related functionalities
Planned Enhancements
The Bank plans to integrate collections capabilities, transaction banking services, procurement solutions, e-commerce integrations and additional business utilities that support day-to-day commercial operations. This evolution is expected to transform KVB Corp into a comprehensive corporate app that serves as a central operating platform for businesses.
Deepening Customer Relationships
We are strengthening customer engagement through a data-driven Customer 360 ecosystem. It combines financial, behavioral and transactional data to create a unified view of customers across products, channels and interactions.
Key benefits include:
- Comprehensive visibility into customer journeys and preferences
- Enhanced relationship management through data-driven insights
- Hyper-personalized product recommendations and service experiences
- Improved understanding of customer needs across touchpoints
We are also implementing a Customer Relationship Management (CRM) platform in phases to transform customer acquisition and relationship management. The platform centralizes:
- Social media-generated leads
- Channel-driven opportunities
- Customer interaction data
To support these initiatives, we have launched an omni-channel marketing platform that unifies customer communications via WhatsApp, SMS and Email, with plans to expand to app notifications, internet banking alerts, and Rich Communication Services (RCS). Unlike conventional campaign-led approaches, this platform allows for ongoing, context-aware and relevant interactions across various channels.
Key capabilities include:
- A single customer view across DLite, ATMs, branches and digital channels
- Channel preference intelligence to optimize communication routes
- Real-time feedback loops to continuously refine interactions
- Timing analytics to identify the most effective engagement windows
To further deepen customer engagement, we are introducing features such as:
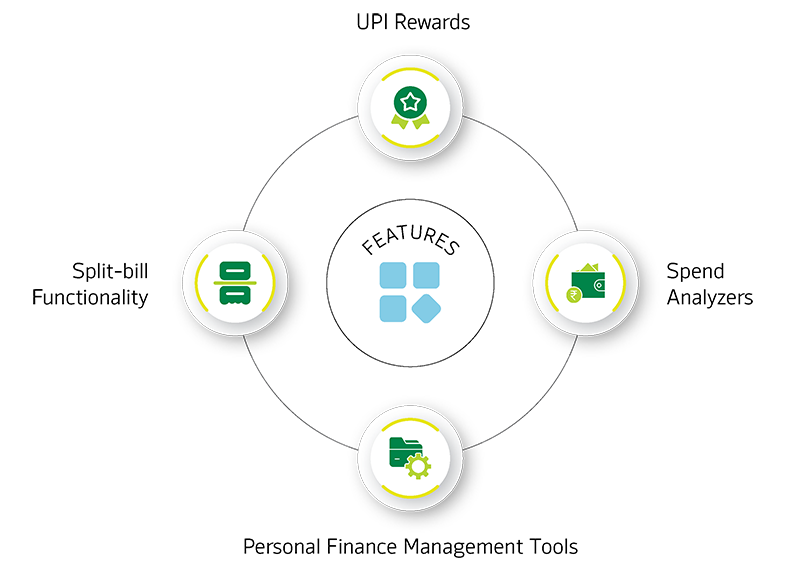
These initiatives are designed to increase customer stickiness, drive higher digital engagement and create additional opportunities for cross-selling and relationship expansion.
Transforming Operations through Process Innovation
We are further enhancing our process capital by re-engineering operational workflows, boosting automation and minimizing manual tasks in critical activities. These initiatives are leading to faster turnaround times, increased productivity and a more scalable operating model.
A key enabler of this transformation is the Helpdesk Management System (HMS). It is a centralized workflow platform that supports branches and back-office functions in managing customer service requests and operational activities. Through real-time monitoring and SLA-driven execution, the platform has significantly improved service responsiveness and operational efficiency.
We have digitized several customer-facing processes to enhance convenience and accelerate service delivery.
- Re-KYC updates can now be completed through DLite, eliminating the need for branch visits
- Implementation of E-Mandates through NPCI's Online Mandate Gateway System enabling customers to authenticate mandates digitally using Aadhaar, Debit Card, PAN or Customer ID credentials, significantly reducing manual intervention and processing timelines
Additional process improvements include:
- SMS optimization initiatives that reduce communication costs
- Migration from physical RSA tokens to the KVB Netshield soft-token platform
- Workflow automation for internal approvals
- Centralized monitoring dashboards that strengthen service delivery and grievance resolution
We are promoting productivity-driven growth with our Centralized Operations Unit model. Standardizing and centralizing routine tasks allow branch teams to concentrate on acquiring customers, providing advisory services and managing relationships.
Looking ahead, we are expanding automation across several areas to further enhance efficiency and scalability.
Key initiatives planned next year
- Productivity enhanced through AI
- Automated HMS workflows
- Paperless password reset capabilities
- Intelligent testing automation
- Chatbot-enabled customer support
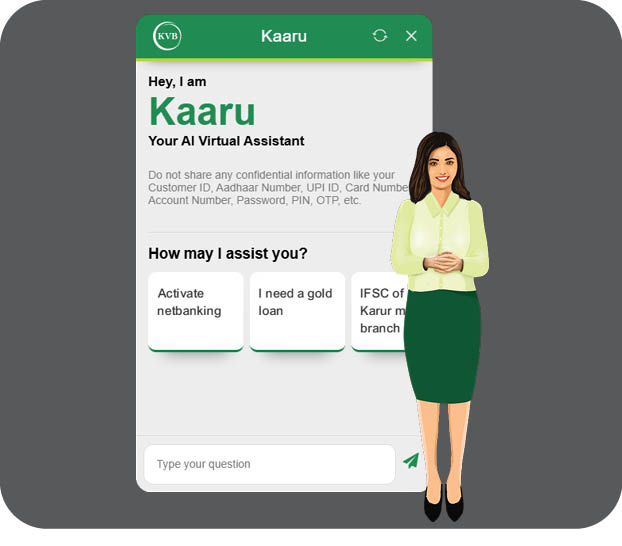
These initiatives are expected to strengthen straight-through processing, optimize operational efficiency and enhance customer service.
Data Analytics
We are strengthening our knowledge capital by harnessing the power of data analytics across the organization. The Bank is establishing an enterprise-wide data foundation that integrates customer, financial, transactional and operational information into a unified analytical environment. This platform will support customer intelligence, business analytics, risk management and decision-making capabilities across the enterprise.
Enterprise Data Foundation
The Bank is building a unified analytical environment that brings together customer, financial, transactional and operational data.
Expanding the Digital Ecosystem through Partnerships
We continue to strengthen our digital ecosystem through partnerships that expand customer reach, improve service delivery and create new growth opportunities. Open banking and API-led integration initiatives planned for seamless connectivity with external platforms and fintech ecosystems, thereby supporting greater innovation and faster delivery of customer-centric solutions.
Strengthening Ecosystem Partnerships
Partnerships with payment platforms are creating new opportunities across merchant acquisition, embedded payments, settlement accounts and digital distribution. These relationships are evolving beyond payment processing to encompass broader ecosystem partnerships that support customer acquisition, CASA growth, and cross-selling opportunities.
Transaction data generated through these ecosystems also enhances customer intelligence, enabling more targeted engagement and helping us deliver relevant products and services to customers.
Enabling Strategic Business Initiatives
The technology function continues to support strategic business priorities through digital enablement and platform integration. Key initiatives include co-lending integrations for affordable housing and the modernization of the Bank's credit card ecosystem, ensuring that technology capabilities remain closely aligned with business growth objectives and evolving customer needs.
Cybersecurity and Governance
As digital adoption accelerates, maintaining trust, resilience and security is essential to our strategy for intellectual capital. The Bank keeps investing in scalable, resilient technology infrastructure focused on reliability, availability and operational continuity. Modern architecture, auto-scaling features and a mobile-first approach enable smooth customer experiences across digital touchpoints.
Strengthening Technology Resilience
We continue to enhance the resilience of our technology environment through investments in infrastructure, disaster recovery preparedness and operational continuity capabilities.
99%
Uptime Maintained in FY 2025-26 across Critical Applications
Advancing Cybersecurity Capabilities
Cybersecurity capabilities continue to be enhanced through a defense-in-depth approach. It combines firewalls, intrusion detection systems, endpoint protection, Security Operations Center monitoring, SIEM-based surveillance, data protection controls and multi-factor authentication.
Additional initiatives that strengthen resilience against evolving cyber threats include:
- Regular Vulnerability Assessment and Penetration Testing (VAPT) exercises
- Red-team simulations
- Phishing drills
- Cybersecurity awareness programs
Governance and Oversight
These capabilities operate within a governance framework anchored by Board oversight and the IT Strategy and Digital Transaction Monitoring Committee. The Committee oversees technology investments, digital monitoring frameworks, operational resilience, audit observations and technology risk management. Together, they ensure close alignment between strategy, risk, compliance and governance.
During the year, the Bank was recognized with 5 awards at the IBA CISO Summit 2025
Cyber Security Team of the Year
Cyber Security Transformation of the Year
Cyber Security Incident Response Maturity
Cyber Security Compliance Champion
CISO Elevator Pitch
Industry Recognition
During the year, the Bank was recognized by the Indian Banks' Association for Best IT Risk Management and Best Digital Financial Inclusion. These awards reflect our focus on secure, innovative and inclusive digital banking.
Outlook
The year ahead will deepen the progress made in FY 2025–26. Customer 360 will move beyond data aggregation to become a more intelligent capability, providing branches and digital channels with a comprehensive view of each customer and enabling more informed engagement. KVB Corp will continue to evolve from a transaction platform into a stronger corporate banking interface, enhancing the experience for corporate customers. The Bank’s AI and analytics capabilities will also play a greater role in fraud detection, credit assessment and collections, helping improve operational efficiency while reducing risk. Our focus is on building a digitally enabled, innovation-driven bank that complements the strengths of fintechs and fosters meaningful partnerships.
Investments in cloud migration, AI-driven fraud monitoring, advanced analytics, intelligent automation, personalized customer engagement and zero-trust cybersecurity will continue to strengthen our digital foundation. At the same time, enhancements to DLite, KVB Corp, CRM capabilities, enterprise data platforms and ecosystem partnerships will help deepen customer relationships, improve service delivery and create new opportunities for growth.